If your reason for buying a property in Dubai includes living there, check the residence route before choosing the property. Permission to own a home and approval of a residence application are separate matters. A sales description mentioning a visa is not a decision from the immigration authority.
This guide is for prospective movers considering property ownership as the basis for residence. It explains the Dubai service pages to consult, the information to check before committing funds, and how to connect a purchase with family and arrival plans.
- Distinguish property ownership, Taskeen residence and property-investor Golden Residence.
- Check the title, ownership share, finance and evidence needed for the intended application.
- Prepare a purchase-and-relocation brief without assuming a guaranteed visa.
First, confirm that you can own the specific property
Dubai Land Department’s ownership guidance identifies freehold areas as the areas where foreign ownership is permitted. Check the specific plot or unit, the form of ownership being offered, and the buyer who will appear on the title. Do not treat every Dubai address or every type of property interest as interchangeable.
A property may suit an investment objective yet be a poor fit for a near-term move. Ask separately about handover, whether you can occupy it, existing tenancy arrangements and the documents available now. If your residence application depends on evidence that will only be issued later, that dependency belongs in the relocation timetable.
Decide when the residence evidence can exist
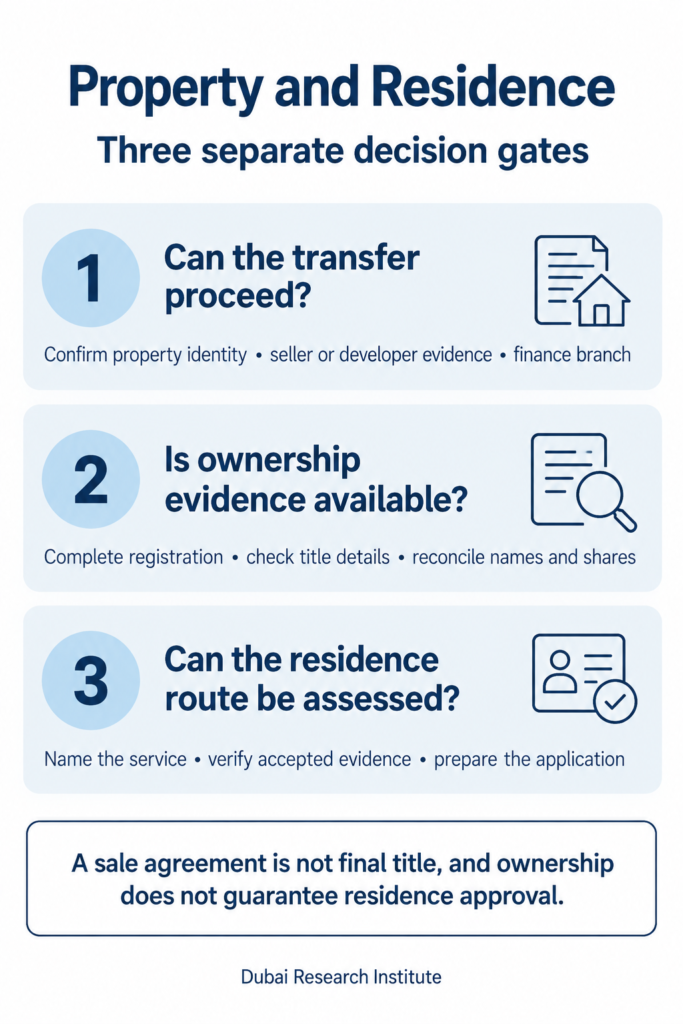
A completed resale, a mortgaged resale and an off-plan purchase produce different property evidence at different times. This article uses that distinction only to identify when a residence-service document may become available; it does not replace the purchase process for the selected transaction.
| Purchase question | Use this guide | Residence dependency to retain here |
|---|---|---|
| Can the proposed buyer own the property? | Buying property in Dubai as a foreigner | Ownership permission and residence eligibility are separate decisions. |
| How will a completed or mortgaged resale transfer? | Ready and resale purchase process | Record when the title and any mortgage evidence required by the selected residence service can exist. |
| What does an off-plan buyer verify and receive? | Off-plan verification and payment checklist | Do not treat booking, SPA or provisional registration as final title or automatic residence evidence. |
| What must the budget include? | Property purchase costs and DLD fees | Keep purchase, borrowing, residence and household costs in separate lines. |
For the residence plan, ask one narrower question: which property document does the named service require, and when can that document exist for this transaction? If the applicant, ownership share, finance arrangement or completion status changes, refresh both the purchase record and the residence-service checklist.
Keep the estate agent, conveyancing or Trustee update in the purchase workstream and the authority response in the residence workstream. A smooth transfer does not decide immigration eligibility, and an advertised residence route does not remove the need for a properly registered purchase.
Compare the current Dubai residence service cards
The following is a comparison of published Dubai service information checked on 7 September 2026. It is a starting point for identifying the application, not a complete eligibility decision.
| Service | What the current Dubai page says | What to confirm for your purchase |
|---|---|---|
| DLD Investor Residence Application (Taskeen) | Lists a two-year permit. Its individual-ownership wording does not set a minimum property value; for joint ownership it specifies an applicant share of at least AED 400,000. | The applicable ownership category and evidence for this unit and applicant. |
| DLD property-investor Golden Visa | Lists a renewable ten-year permit and a property purchase-value threshold of AED 2 million. Mortgage cases require bank evidence. | Accepted valuation and ownership evidence, mortgage treatment and the duration issued through the selected Dubai service. |
Older online guides may quote different Taskeen thresholds. Use the current service card and ask DLD to confirm your case. The current wording allows an application; it does not promise that every property or applicant will be approved.
GDRFA also publishes a property-owner residence service with conditions covering a completed, habitable, fully owned property and income of AED 10,000 per month or demonstrated financial solvency. Ask which service applies to your application. Do not add that page’s conditions to a Golden Visa checklist or assume different service pages describe independent entitlements you can freely combine.
Resolve mortgage and duration questions before relying on them
Official summaries currently differ. GDRFA Dubai’s investor Golden Residence page describes a ten-year route and accepts mortgaged property. The federal ICP Golden Residency overview lists five years for real-estate investment and refers to ownership without loans. These sources should not be presented as one uniform rule.
DLD’s Golden Visa page also uses different wording about mortgage payments: its introduction refers to AED 2 million paid, while its terms request a bank no-objection letter showing the amount paid and the balance. Before signing a purchase or finance agreement in reliance on residency, obtain confirmation from the relevant Dubai authority for the proposed property, paid amount and outstanding loan.
Keep that confirmation with the property documents. A clear question is: “For this ownership structure and mortgage balance, which residence service can I apply through, what evidence is accepted, and what duration would apply?” A general assurance that the property is “visa eligible” leaves those decisions unanswered.
Create a short property and residence check sheet
- Property: record the unit or plot reference, title status, seller, completion status and intended use.
- Ownership: record who will own it and each person’s share. Ask how the selected residence service assesses that arrangement.
- Finance: separate the purchase value, amount paid and outstanding borrowing. Request the bank documents specified for the route.
- Timing: identify when the required ownership evidence becomes available and which application steps require you to be in Dubai.
- Household: list accompanying family members and check their application requirements separately.
- Ongoing commitments: ask about property charges, insurance, residence renewal and what selling or changing ownership would mean for your status.
Use the sheet to compare properties on the same basis. A higher price, longer advertised visa term or attractive payment schedule is not enough to show which option fits your plans. Keep the home’s suitability, the financial commitment and the immigration decision visible as separate considerations.
Prepare the application without assuming it can all be remote
The Taskeen checklist includes a passport, electronic title deed, photograph and a Dubai-issued Good Conduct Certificate addressed to DLD, with existing identity or immigration documents where available. It requires the applicant to attend personally. Confirm the full current list for the chosen service before arranging appointments.
The DLD Golden Visa service requires the applicant to be inside the UAE and does not permit an adviser to apply in the applicant’s place. Plan support around document preparation and coordination while allowing for your own required attendance.
Keep property-transaction spending separate from immigration and household spending. Request itemised, current figures for the purchase and registration, any borrowing, service charges, applications, document attestation, medical and identity steps, insurance and professional support. This guide does not quote a universal total because the relevant items depend on the property, route and family.
Connect residence approval with the move itself
Work backwards from the point when your household needs a usable home, school places and health cover. Allow temporary accommodation if property access or the application takes longer than planned. Our family checklist helps coordinate these dependencies; the UK guide covers UK-specific departure administration.
If you also intend to establish a business, review the company setup and residence guide. A property-based residence plan does not answer which business licence your activity needs.
Discuss the property route with DRI
DRI supports people considering a move through property purchase or company formation. Read our relocation support overview, then describe your current country, move timing, whether you have selected a property, the intended ownership and any accompanying family. You can start with an outline; identity documents are not needed in the initial enquiry message.
Official sources checked on 7 September 2026. Property, immigration and financing decisions depend on the applicant and transaction. Confirm the applicable requirements with the competent authority before committing to a purchase on the basis of residence eligibility.